


Major Management Challenges Facing the IRS
Each year, we evaluate IRS programs, operations, and management functions to identify the most vulnerable areas in the Nation’s tax system.
For Fiscal Year (FY) 2027, we have identified seven management and performance challenges facing the IRS. Download the report or select one of the challenges below to learn more.
The Challenge
Between January 2025 and January 2026, the number of IRS employees decreased from approximately 103,000 to 74,000 (30 percent). Although this is consistent with historical staffing, the reductions occurred rapidly and resulted in the departure of many experienced employees.
In addition, the enacted FY 2026 budget reduced IRS’s annual funding by approximately 20 percent. Although the Inflation Reduction Act of 2022 (IRA) previously provided the IRS with nearly $80 billion in supplemental funding over a 10-year period, Congress subsequently reduced it to $26 billion. As of March 31, 2026, the IRS has spent $16.5 billion of its IRA funds (64 percent).
Completing modernization projects, providing quality service to taxpayers, and enforcing tax laws with a reduced workforce and budget are challenges for the IRS. For example, we reported that the IRS started 30 percent fewer taxpayer examinations in FY 2025 compared to FY 2024. Further, examination closures and additional tax assessments proposed by the IRS’s Small Business/Self-Employed Division notably declined during the period that coincided with workforce reductions. Therefore, the IRS needs to continue leveraging technology to deliver on its mission cost effectively. In particular, the IRS will need to continue introducing and adopting greater use of automation, super intelligence (SI), and other technology-based tools and solutions to help offset IRS workforce reductions and enhance tax collections.
Although technology offers many opportunities, the IRS will still need to hire employees for certain core operations. However, a new hiring process delayed the posting of job announcements for employees the IRS was seeking to hire for the 2026 Filing Season. We reported that as of February 27, 2026:
- The Submission Processing function (which processes tax returns) was unable to hire about 58 percent (1,100 of 1,900) of its approved positions.
- The Accounts Management function (which handles taxpayer contacts and adjusts tax accounts) was unable to hire 34 percent (1,200 of 3,500) of its approved positions.
In addition, these functions were unable to onboard and train all the individuals they hired before the filing season began.
To compensate for staffing reductions, the IRS required employees in certain divisions to work overtime to help manage increases in key tax return processing inventories. Comparing January through September for Calendar Years 2024 and 2025, paid overtime hours increased by 12 percent. This resulted in a year-over-year increase of approximately $27 million in overtime costs.
Strategic recruitment and hiring will be important to ensure the agency can provide top-quality service to taxpayers, ensure compliance, and deliver a successful filing season.
IRS Progress
During the 2026 Filing Season, we found the agency expanded its use of technology to streamline tax return processing. The IRS began converting paper tax returns into a digital format so they could be electronically processed, expanded its use of an automated tool that corrects specific errors on a tax return, and automated the processing of some amended tax returns.
Taxpayers are increasingly relying on IRS self-service tools. We found that the number of online account users exceeded 64 million in 2026 (an increase of nearly 13 million users from the prior year). An online account allows taxpayers to view specific details about their federal tax account, such as their balance, payment history, digital notices, and audit status.
In addition, the IRS began to backfill select positions. As of January 2026, approximately 2,000 employees have been hired. The IRS will continue to use its Direct Hire Authority, which eliminates certain steps in the hiring process, to fill these positions. The IRS also announced a new initiative (the One IRS Initiative) that trains existing employees to temporarily assist other functions as needed. However, the results of this effort are currently unknown.
Further, the IRS is using SI to help offset IRS workforce reductions and enhance tax collections. For example, the IRS is developing Taxpayer 360, which will provide intuitive, SI-enabled tools, and user-friendly interfaces to enable more efficient issue resolution for taxpayers and the IRS.
Key Recommendations Implemented
- The IRS implemented several of our recommendations to improve its new employee onboarding program. This is important given that the IRS has resumed selected hiring, and it may help improve the likelihood that new employees remain with the agency.
- When taxpayers need the IRS to adjust their tax accounts, the IRS office that makes the adjustment is required to send all documentation supporting the adjustment to one of its Tax Processing Centers. To address a backlog, the IRS executed a plan to rebalance certain workloads across the Tax Processing Centers.
Ongoing Work
Given the extent of staffing and funding reductions, we will review the IRS’s performance during the 2027 Filing Season and its efforts to use enhanced technology to improve tax compliance in its Examination and Collection functions.
We will also assess whether the IRS’s succession planning strategically addresses staffing losses and complies with recent executive orders and initiatives. In addition, we will evaluate the IRS’s staffing and reassignment strategy (including the One IRS Initiative) to achieve customer service goals and the effectiveness of controls over and use of premium pay, including mandatory overtime.
The Challenge
The IRS accumulates vast amounts of data as it annually processes hundreds of millions of tax returns and other forms. Much of this data is sensitive and stored in different computer systems available to IRS employees and contractors. However, preventing unauthorized access to, and disclosure of, sensitive taxpayer information continues to be a challenge for the IRS.
Specifically, we found that some IRS employees who were on administrative leave because they accepted the Deferred Resignation Program either 1) continued to retain access to the IRS’s network or sensitive systems 2) did not return their hardware or equipment or 3) accessed an IRS facility. Additionally, we found that more than half of the nearly 1,200 employees and contractors hired between January and August 2025 did not complete appropriate security awareness training before gaining access to sensitive systems.
Insufficient controls at ZPI contractor sites increased the risk of unauthorized access to taxpayer data. We reported that employees at ZPI contractor sites accessed areas with taxpayer information without being authorized by the IRS. For example, the perimeter fence and the loading dock used to receive taxpayer information were open and not properly secured. Additionally, security vulnerabilities in contractor software were not timely resolved.
Another March 2025 Executive Order, Stopping Waste, Fraud, and Abuse by Eliminating Information Silos, aims to remove barriers and promote interagency data sharing. This may accelerate data sharing between the IRS and other agencies, a trend that has already significantly increased over the last two decades. For example, we identified more than 1,100 known data sharing agreements between the IRS and external organizations that receive Federal Tax Information (FTI). Most of these agreements support state and local tax administration. However, the IRS cannot readily identify all data sharing agreements because it lacks a centralized database. Specifically, the IRS office responsible for managing these agreements was unaware of 30 additional FTI-related agreements established by other IRS business units.
In addition, we found that the Department of Homeland Security (specifically Immigration and Customs Enforcement) did not meet safeguarding standards before signing a data sharing agreement with the Department of Treasury. As a result, there is a potential risk that Immigration and Customs Enforcement could fail to properly safeguard taxpayer data it received from the IRS.
IRS Progress
The IRS addressed 22 prior recommendations to improve the security of data placed in the cloud (cloud-computing enables convenient, on-demand network access to a shared pool of configurable computing resources, such as networks and servers).
After we identified security vulnerabilities in the information systems used to process taxpayer information at some ZPI contractor sites, IRS management developed a monthly review process to identify un-remediated aged vulnerabilities for applicable updates. For example, we found that a system was using a version of software that was no longer supported by the vendor. This is a critical vulnerability because unsupported software will no longer receive security updates, which increases the risk that the software could be exploited using known weaknesses.
Key Recommendations Implemented
The IRS has:
- Reviewed existing rules and policy within the Data Loss Prevention tool to prevent taxpayer information from being sent externally and identified additional rules or controls to be implemented to improve data security. They implemented additional rules, policy, and controls along with ongoing monitoring and reporting.
- Ensured a process is in place to validate that all audit trail data elements, including investigative elements provided by TIGTA Office of Investigations, are being captured.
- Ensured that access to sensitive systems is immediately suspended or disabled when a contractor is identified as not having a favorable background determination. Further, the 6 IRS is evaluating the feasibility of streamlining the access removal process, which requires integrating different IRS and Treasury Department systems.
Ongoing Work
We plan to assess the IRS’s efforts to provide effective governance, management, and oversight of SI implementation. We also plan to assess contractor compliance with cybersecurity controls as well as physical security of taxpayer data at contractor and Volunteer Income Tax Assistance sites. We will also evaluate controls to ensure Credentialed Service Providers (these are entities authorized to issue, manage, and validate digital or electronic credentials) are meeting requirements and following industry best practices for identity proofing.
The Challenge
The Working Families Tax Cuts Act (WFTC) created four new individual tax deductions related to tips, overtime compensation, car loan interest, and senior deductions. Because the legislation was enacted shortly before Filing Season 2026, the IRS had limited time to develop taxpayer guidance, update tax forms and information reporting, and implement submission processing and compliance controls.
Although the IRS generally implemented select WFTC provisions successfully, we identified some limitations in the IRS’s guidance, processing controls, and compliance strategy. For example, we determined that the guidance for the overtime deduction did not explain certain exemption rules, increasing the risk that taxpayers may incorrectly determine eligibility for the deduction.
Additionally, we identified significant limitations in controls related to the car loan interest deduction. As a result, we identified that the IRS accepted more than 470,000 returns claiming $977 million in questionable deductions (with a total estimated tax effect of $122 million).
IRS Progress
New and modified e-file business rules (which the IRS uses to identify errors on electronically filed tax returns when they are filed) associated with the Child Tax Credit, State and Local Tax Deduction, and Adoption Credit are working as intended. We found the IRS was accurately rejecting tax returns when applicable and determined whether any tax returns that should have been rejected were accepted for processing.
The IRS also continued to implement the provisions of prior legislation. For example, the IRS implemented actions to address previous concerns we reported about the processing of Qualified Small Business Payroll Tax Credit claims. Additionally, the IRS took action to address errors brought to their attention by taxpayers that prevented them from reporting the maximum allowed credit.
Key Recommendations Implemented
- The Taxpayer First Act of 2019 changed the name of the “Office of Appeals” to the “IRS Independent Office of Appeals.” In response, the IRS updated more than 150 forms, publications, and letters sent to taxpayers, prioritizing updates to external-facing materials to underscore to taxpayers and representatives that their appeal is being heard by an independent function within the IRS.
- The IRS evaluated the expanded use of soft notices to address potentially erroneous Premium Tax Credit claims. In addition, it evaluated potential treatments for notifying taxpayers of potential Premium Tax Credit benefits to which they may be eligible.
Ongoing Work
We are evaluating the IRS’s efforts to implement tax provisions to remove certain tax benefits for non-citizens. We will also follow up on prior recommendations related to Opportunity Zones and Qualified Business Income Deductions and assess the implementation of newly enacted changes to both benefits.
The Challenge
Every year, millions of taxpayers seek assistance from the IRS via its website, telephone helplines, Taxpayer Assistance Centers, social media platforms, and more. These various service channels should help taxpayers quickly, accurately, and without the need for additional contact. However, taxpayers do not always receive the quality service they deserve.
For example, we estimated (based on a sample of 200 call recordings we reviewed) that approximately 1 million taxpayers that called certain IRS telephone lines between February and May 2025 did not receive quality service. Some IRS representatives were unprofessional or used technical jargon, and some taxpayers received inaccurate information. Additionally, some calls were disconnected, dropped, or not transferred.
In lieu of calling the IRS, taxpayers can use chat applications to exchange text messages, files, web pages, and other information with IRS assistors. However, the IRS has not sufficiently evaluated the effectiveness of chat applications used by its Automated Collection Service function. Compounding this issue, the data currently collected to measure program performance is unreliable, limiting the IRS’s ability to determine if the program is operating effectively. We also found that many live assistors worked multiple chats concurrently, which can affect customer service and increase the risk that taxpayer information will be inappropriately disclosed to another taxpayer.
Taxpayers that are potential victims of identity theft continue to face lengthy delays in resolving their cases. For example, identity theft cases take nearly two years, on average, to close. We found that most of this time is spent waiting for an assistor to become available to work the case. These delays are burdensome for victims and costly to the government. For example, we determined that over a two-year period, the IRS paid more than $124 million in refund interest to taxpayers. In addition, the loss of nearly 300 trained identity theft assistors to the Deferred Resignation Program, combined with the continued receipt of new cases, may make it more difficult for the IRS to reduce processing times.
Quality taxpayer service extends to respecting taxpayers rights. We are required to annually report on the IRS’s compliance with provisions that restrict direct contact with represented taxpayers. In most cases, the IRS must suspend an interview when a taxpayer requests to consult with a representative, such as an attorney. However, we continue to find it difficult to determine if the IRS complies with direct contact requirements because the agency lacks a system to identify potential violations. Additionally, our interviews with some managers and employees revealed an inconsistent understanding of certain procedures, such as a taxpayers’ right to audio record in-person interviews related to the determination or collection of taxes.
IRS Progress
The IRS has added payment options to help make payments easier for individuals and business taxpayers. For example, the Direct Pay option added additional electronic tax forms that businesses can use to make payments without needing to register an account.
In December 2023, the IRS announced that it would waive the Failure to Pay penalty that accrued during the pandemic when automated collection notices were suspended. The penalty relief period ended in March 2024. We reported that the IRS accurately identified and issued penalty relief to more than 99 percent of the 4.9 million taxpayers who were eligible.
IRS employees generally protect taxpayers’ rights when taking enforcement actions. For example, we reported that the IRS complied with the requirement to notify taxpayers of their right to a Collection Due Process hearing when filing a tax lien. Revenue officers also provided the required notice and challenge period for more than 98 percent of levies we reviewed.
Key Recommendations Implemented
- The IRS implemented appropriate procedures to track receipts, rejections, closures, and substantiations for unidentified taxpayer payments. We made this recommendation because the IRS did not have processes to track these types of payments and monitor their resolution. Unidentified payments are payments the IRS receives but cannot associate with the correct taxpayer or tax period.
- The IRS Independent Office of Appeals worked with relevant stakeholders to develop procedures for addressing prohibited levy actions involving tax periods for which a taxpayer requests a levy Collection Due Process hearing under Internal Revenue Code section 6330(b).
Ongoing Work
We will determine if training adequately prepares Customer Service Representatives to provide quality service. We plan to evaluate the readiness of local Taxpayer Advocate Service telephone lines and the consistency of information posted online. We also plan to assess taxpayers’ experience authenticating across various channels (in person, telephone, and online).
The Challenge
The modernization of IRS information technology (IT) and business systems is essential to fulfilling its mission of providing America’s taxpayers with top quality service, helping them understand and meet their tax responsibilities, and enforcing the law with integrity and fairness. However, the IRS has a history of cost overruns and delays in its IT modernization efforts.
As the IRS modernizes its systems, adequate security controls must be in place to manage access to sensitive taxpayer data. The IRS transitioned to SharePoint Online (SPO) to modernize its technology and improve efficiency and collaboration across the enterprise. However, 99 percent of the more than 18,000 SPO sites we reviewed were either missing audit logs or did not report an access control method. In addition, the IRS could not migrate a scanning tool it uses to identify sensitive information (e.g., Personally Identifiable Information or Federal Tax Information) that should not be stored on SPO sites. As a result, some files containing sensitive information were accessible to SPO users. Lastly, the migration to SPO took two years longer than originally scheduled, costing the IRS $1 million to maintain its older system.
We reported similar issues with the Enterprise Data Platform, which was deployed to improve data storage and management in support of improved taxpayer services and enforcement. Because of integration issues, none of the platform’s privileged user accounts are managed by the Privileged User Management Access System as required by the IRS’s policy. In addition, the IRS was unable to provide us with any evidence that privileged user accounts were monitored.
IRS Progress
The IRS continued advancing transformation efforts in 2026. These advancements include modernizing tax account processing, promoting agility across operations, implementing new technology solutions, strengthening network communications, reinforcing enterprise security, and enhancing operations.
The IRS also continues to make progress with its recently developed Information Returns Intake System (IRIS), which will replace a similar legacy system. In short, IRIS allows taxpayers to file Forms 1099 through two different submission methods. The IRS established tools to share with and assist stakeholders in using IRIS, including conducting forums and engaging with state tax administrators and others to introduce and provide updates about IRIS. The agency also held monthly IRIS working group meetings with state participants, tax return transmitters and preparers, and software developers to help users avoid filing errors and address known issues.
Key Recommendations Implemented
The IRS continues to expand its use of SI, which has the potential to improve everyday operations of the IRS as well as creating operational efficiencies and more effective ways to deliver tax administration. In response to our recommendation, the IRS improved its SI governance framework. For example, the agency hired additional IRS employees to support the governance functions and refined approval procedures for SI use cases based on lessons learned. These actions will help ensure the safe, secure, and trustworthy development and use of SI.
Ongoing Work
We plan to assess the impact of the IT organization restructuring on the IRS’s transformation goals. We also plan to evaluate whether the IRS properly identified IT systems that met its revised legacy definition and used this information to inform its modernization plans. We also plan to assess the quality of data managed by the Enterprise Data Platform.
The Challenge
One of the IRS’s key responsibilities is to ensure taxpayer compliance with the Internal Revenue Code. This is important because small declines in compliance cost the government billions of dollars in lost revenue and shift the tax burden from those who do not pay their taxes to those who pay on time every year.
However, examination rates have decreased for certain taxpayer segments. For example, the IRS’s examination rate for partnerships with at least $10 million in total assets decreased from 2.7 percent in 2011 to less than 0.1 percent in 2023. We recently reported that the IRS’s Large Partnership Compliance Program began using SI to better identify partnerships for potential examination, which could help lower no-change rates (i.e., the examination produced no tax adjustments to the partnership’s return). However, 92 percent of the program’s closed examinations resulted in no changes. Although preliminary, these results indicate that the IRS may need to continue to further refine its selection models to ensure that it is selecting returns with the highest compliance risk.
The gross Tax Gap is the estimated difference between the amount of tax owed, and the amount paid voluntarily on time. For Tax Year 2022, the projected gross Tax Gap was $696 billion. Approximately $63 billion (9 percent) is due to nonfilers (taxpayers who do not timely file a required tax return). The IRS generally sends two notices requesting that selected nonfilers file a return. However, we recently reported nearly 33,700 taxpayers remained in first notice status, preventing further collection action. We estimate that continuing the enforcement process on these taxpayers could result in secured returns or tax assessments for nearly 10,500 cases involving 9,100 taxpayers and approximately $321 million in potential additional tax due. After we raised this issue, the IRS moved the cases out of first notice status in March 2026.
Certain refundable tax credits remain challenging for the IRS to administer because it has limited ability and information to timely verify taxpayer eligibility. The IRS has not reduced the improper payment rate estimates to less than 10 percent (the goal required by the Payment Integrity Information Act) for any of its reported high-risk programs. In FY 2025, the IRS estimated an overall improper payment rate of 26.5 percent and estimated improper payments totaling $28.1 billion for the Additional Child Tax Credit, American Opportunity Tax Credit, Earned Income Tax Credit (EITC), and Net Premium Tax Credit.
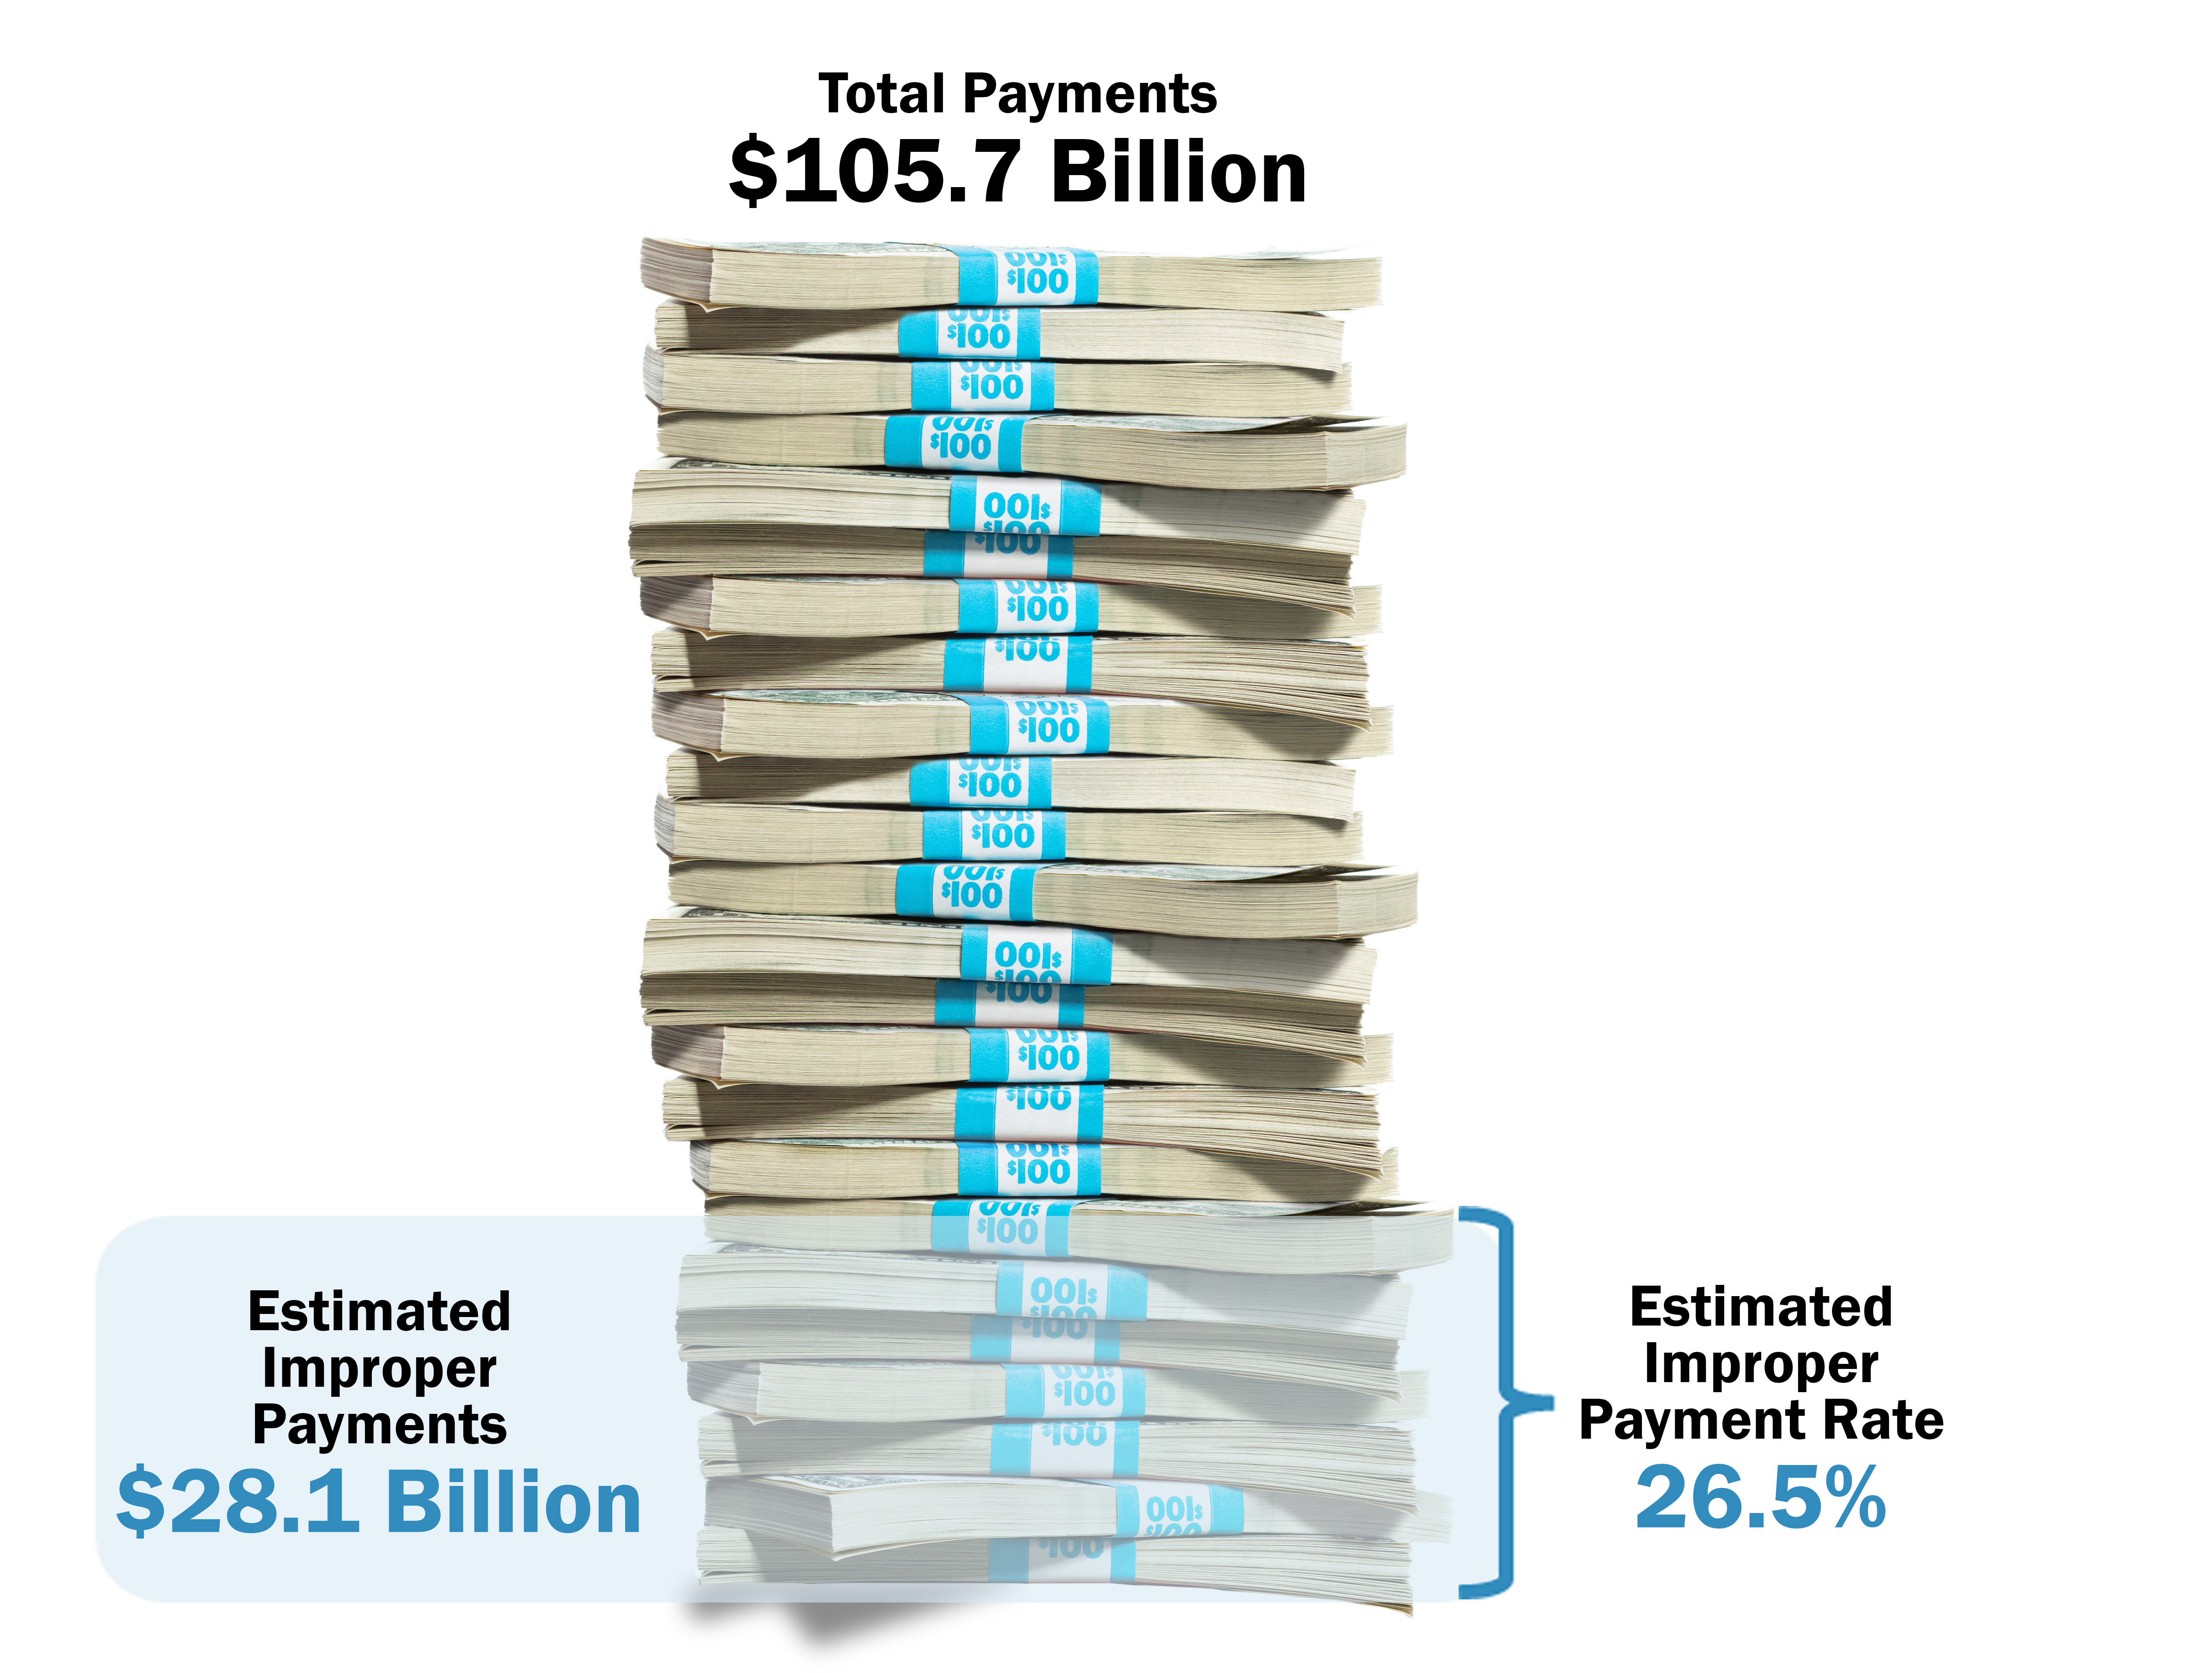
Four High-Risk Programs
IRS Progress
For Calendar Years 2024 and 2025 (as of November 2025), the IRS protected $7 billion in fraudulent tax refunds related to individual identity theft fraud. The IRS also continues to benefit from external partnerships that share real-time alerts about fraud schemes. The IRS subsequently adjusts existing or implements new identity theft filters based on information received from these alerts. These alerts have contributed to almost $278 million in protected revenue since 2017. For example, the IRS updated three other identity theft filters that addressed the Sick and Family Leave Credit, Fuel Tax Credit, and high-income tax withholdings.
The IRS also made progress preventing ineligible individuals with a nonwork Social Security Number (SSN) from receiving the EITC. This progress was accomplished manually because the IRS does not have sufficient or reliable data to systemically prevent these individuals from receiving the credit. For Processing Years 2023 and 2024, the IRS manually examined 5,100 tax returns with nonwork SSNs and found that nearly 90 percent of these selected tax returns were ineligible to claim the EITC. As a result, the IRS protected almost $11 million in revenue.
Key Recommendations Implemented
- After we reported that the IRS could collect over a billion dollars in unreported wagering income, the agency conducted an environment scan of the current and potential future conditions of the sports betting and online gambling industries, the industries’ risks and impact on tax compliance, and updated existing or created new charters to identify noncompliance.
- In response to our finding that vague and outdated guidance created challenges for the IRS to oversee tax-exempt hospital oversight, the IRS shared our report with the Department of the Treasury Office of Tax Policy. This collaboration is important because it could lead to a legislative proposal to amend appropriate provisions of existing law to clearly and specifically define community benefit, a standard that must be satisfied to obtain and maintain status as a tax-exempt organization.
Ongoing Work
We will evaluate the IRS’s efforts to identify taxpayers with significant Form 1099 income who do not file tax returns. We also plan to evaluate the use of SI to select cases for review in the Examination and Automated Underreporter Programs.
We also plan to assess the strengths and weaknesses of the Office of Fraud Enforcement in the IRS’s overall strategy to combat fraud.
The Challenge
A March 2025 Executive Order, Modernizing Payments to and From America’s Bank Account, mandates the transition to electronic payments for all federal disbursements and receipts (with limited exceptions) to help reduce fraud. As a result, the IRS must issue refunds to taxpayers electronically and only accept electronic payments from taxpayers.
However, there are several challenges the IRS must overcome to help increase the number of taxpayers that send or receive electronic payments. Some of these challenges are acknowledged in the executive order, including taxpayers who are unbanked, hold certain religious beliefs (which would exempt them), or have limited access to technology. In addition, we found that the IRS needs to further increase public awareness, modify additional tax forms to allow taxpayers to include bank account information, notify affected business taxpayers, and update tax account features for businesses so they can provide banking information.
In January 2025, the President issued a Return to In-Person Work directive requiring executive branch agencies to take steps, as soon as practicable, to end remote work arrangements and require employees to return to full-time, in-person work. However, the IRS may encounter several challenges assessing its compliance with the return-to-office directive.
For example:
- IRS employees may routinely perform tasks outside of a normal in-office setting, which makes it difficult to confirm if the employee is complying with return-to-office policies. For instance, revenue officers frequently conduct face-to-face interviews with taxpayers outside the office.
- The IRS cannot easily verify whether its employees worked a full in-office day because not all offices require employees to badge in and out.
- Some IRS employees are assigned to locations without access card data.
We also reported in February 2026 that the IRS has made limited progress implementing the Zero Paper Initiative (ZPI), which aims to digitize paper tax returns and correspondence. After delays selecting contractors, the ones supporting the initiative have not been able to hire enough staff. And for those they have hired, the staffing cuts at the IRS have made it difficult to provide the required clearances on time. As a result, contractors have yet to scan large volumes of paper-filed tax returns.
IRS Progress
The agency continues to make progress adopting technologies—like SI—to administer the tax system more effectively. As of November 2025, the IRS reported 175 projects that involve the use of SI to improve overall IRS operations, customer service, and enforcement. For instance, the IRS piloted automation to process amended tax returns during the 2026 Filing Season.
To implement paperless disbursements and receipts, the IRS:
- Created a notice (the CP53E) to send to taxpayers who either did not provide a direct deposit account on their tax return or provided an incorrect direct deposit account. As of March 31, 2026, the IRS issued more than 1.9 million CP53E notices to taxpayers.
- Designated an informational toll-free line with message prompts explaining the new direct deposit process and what actions to take. As of March 28, 2026, there were 351,957 calls to this toll-free line.
- Updated the Individual Online Account so taxpayers can add a direct deposit account. As of March 26, 2026, the IRS reported that 469,290 taxpayers updated their direct deposit
Key Recommendations Implemented
- The IRS entered into an interagency agreement to develop a new grants management system for the Low-Income Tax Clinic Program Office. This will streamline processes by centralizing operations, reducing manual tasks, and minimizing reliance on other systems. Previously, we reported that the process and procedures used to administer and monitor Low-Income Tax Clinic grants are a manual and labor-intensive process.
- Deployed a new Taxpayer Advocate Service case and systemic issue management system that includes dashboard and reporting features that will allow case advocates and managers to more effectively monitor the status of requests and take appropriate follow up actions. The system also includes an automated process to keep congressional staff informed about the status of their cases.
Ongoing Work
We will continue to evaluate the IRS’s efforts to modernize paper processing of tax returns, correspondence, and information documents.
Sufficient contracting practices are critical to efforts to automate systems and processes. We will evaluate whether Blanket Purchase Agreements awarded and administered by the IRS comply with procurement regulations and IRS policy. Given declining IRS budgets, we will also assess the costs, benefits, and barriers to expanding the Private Debt Collection program.